Introduction: Student Loan Debt Can Feel Overwhelming, But You Need a Plan
Graduating from college should feel like the beginning of a new chapter. You have a degree, new career opportunities, and plans for your future. But for many Americans in their 20s, that excitement comes with an uncomfortable reality: student loan debt.
Monthly payments can compete with rent, groceries, transportation, emergency savings, and other financial priorities. When several loans have different balances, interest rates, and due dates, it can become difficult to know where to start.
The good news is that you do not have to repay everything at once. You need a clear repayment strategy, a realistic budget, and a consistent approach.
Two popular strategies are the Debt Snowball Method and the Debt Avalanche Method. Both help you organize multiple debts and direct extra payments toward one loan at a time. However, they use different approaches.
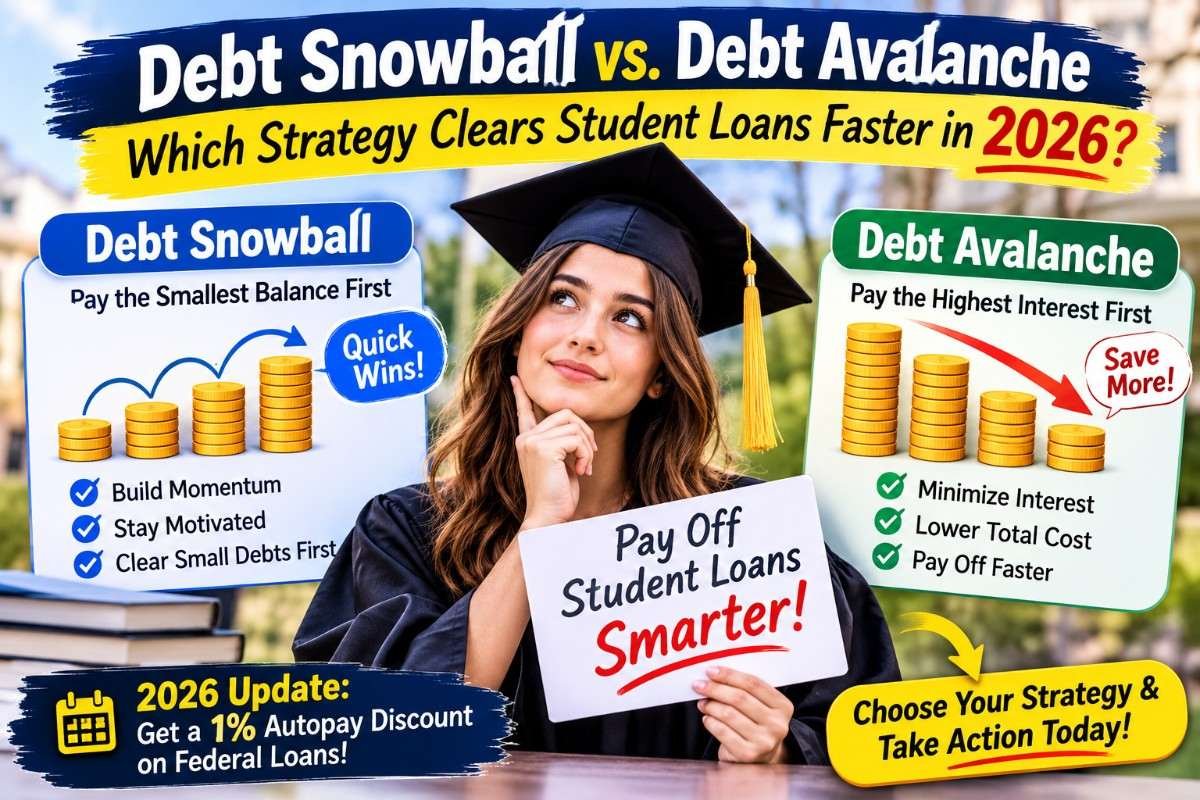
The snowball method prioritizes the smallest balance, while the avalanche method prioritizes the highest interest rate.
So, which one helps you clear student loans faster in 2026?
The answer depends on your loan balances, interest rates, available monthly payment, and what helps you stay consistent. Let’s compare both methods so you can choose a strategy based on your financial situation.
Strategy 1: The Debt Snowball Method
The Debt Snowball Method focuses on paying off your smallest debt balance first, regardless of its interest rate.
You continue making the required minimum payments on every loan. Then, you put any extra money you can afford toward the loan with the smallest remaining balance.
Once that loan is completely paid off, you take the amount you were paying toward it and add that money to the next-smallest loan.
This creates a snowball effect: your payment toward the next debt becomes larger as you eliminate individual loans.
How the Debt Snowball Method Works
Imagine you have the following three student loans:
| Student Loan | Outstanding Balance | Interest Rate |
| Loan A | $2,000 | 5.5% |
| Loan B | $5,000 | 7.0% |
| Loan C | $9,000 | 6.0% |
With the snowball method, you arrange your loans from the smallest balance to the largest:
- Loan A: $2,000
- Loan B: $5,000
- Loan C: $9,000
You continue making minimum payments on all three loans while directing your extra repayment money toward Loan A.
After paying off Loan A, you redirect the money you were using for that loan toward Loan B. Once Loan B is eliminated, you focus on Loan C.
Your total monthly debt budget stays consistent, assuming your income and expenses remain unchanged.
Why the Debt Snowball Method Can Work
The biggest advantage of the snowball method is psychological momentum.
Student loan repayment can take years. When you make payments month after month without seeing an individual loan disappear, it can be difficult to feel that your efforts are making progress.
The snowball method gives you smaller milestones along the way.
Here are its main benefits:
- Quick repayment milestones: Smaller balances may be eliminated sooner, depending on your payment amount.
- Visible progress: Every paid-off loan gives you a clear achievement.
- Simpler debt management: You gradually reduce the number of individual loans.
- Motivation to stay consistent: Early progress can make a long repayment journey feel more manageable.
For someone who struggles to stay motivated, these smaller wins can make a meaningful difference.
The Biggest Disadvantage of the Snowball Method
The snowball method does not prioritize interest rates.
For example, you might have a $2,000 loan charging 5.5% interest and a $5,000 loan charging 7% interest. The snowball method tells you to focus on the $2,000 loan first.
Mathematically, that may not be the most cost-effective decision.
While you are paying down the smaller loan, the larger loan with the higher interest rate continues accruing interest.
As a result, the snowball method can cost more in total interest than the avalanche method when other repayment conditions are equal.
Best for: Recent graduates who value visible progress, have several small balances, or need early milestones to stay committed to repayment.
Strategy 2: The Debt Avalanche Method
The Debt Avalanche Method takes a different approach. Instead of looking at the loan balance, it prioritizes the interest rate.
You make the required minimum payments on all your loans. Then, you direct your extra repayment money toward the loan with the highest interest rate.
After that loan is paid off, you move to the next-highest interest rate.
This process continues until every targeted loan is repaid.
The main goal is to reduce the amount of interest that accumulates while you are repaying your debt.
How the Debt Avalanche Method Works
Let’s use the same student loan example:
| Student Loan | Outstanding Balance | Interest Rate |
| Loan A | $2,000 | 5.5% |
| Loan B | $5,000 | 7.0% |
| Loan C | $9,000 | 6.0% |
With the avalanche method, you arrange the loans by interest rate:
- Loan B: 7.0%
- Loan C: 6.0%
- Loan A: 5.5%
You continue making minimum payments on every loan and direct extra money toward Loan B.
After paying off Loan B, you redirect that extra payment toward Loan C. Finally, you focus on Loan A.
This approach prioritizes the debt that is costing you the most in interest.
Why the Debt Avalanche Method Can Save Money
Interest is one of the biggest reasons student loan balances can take years to eliminate.
When a loan has a higher interest rate, it generally accumulates interest faster than a comparable loan with a lower rate.
By prioritizing the highest-rate loan, the avalanche method reduces the amount of high-interest debt sooner.
Here are its main benefits:
- Lower total interest: It generally minimizes interest costs when you have the same repayment budget and no special loan benefits change the calculation.
- Mathematical efficiency: Your extra payments target the most expensive interest rate first.
- Potentially faster payoff: Under comparable repayment conditions, it can reduce the time needed to eliminate all your debts.
- A logical repayment order: You choose your next target based on the cost of borrowing rather than the size of the balance.
For graduates who are comfortable following a longer-term plan without needing frequent small wins, this method can be especially useful.
The Biggest Disadvantage of the Avalanche Method
The avalanche method can feel slow at the beginning.
Imagine your highest-interest loan has a balance of $9,000, while another loan has a balance of only $1,500.
Even if you make consistent extra payments, the $9,000 loan may take much longer to eliminate. You might not see a loan completely disappear for quite some time.
That can make it harder to stay motivated if you prefer visible progress.
Best for: Graduates who want to minimize interest costs, have high-interest student loans, and can stay consistent even when early milestones take longer.

Head-to-Head Comparison: Debt Snowball vs. Debt Avalanche
Both methods can help you organize student loan repayment. The main difference is how you decide which loan receives your extra money.
Here is a quick comparison:
| Comparison Factor | Debt Snowball | Debt Avalanche |
| Focus | Smallest balance first | Highest interest rate first |
| Main Benefit | Quick psychological wins and motivation | Lower total interest costs |
| Who It Is Best For | People who need visible progress to stay consistent | People who prioritize mathematical savings |
| Payment Priority | Balance amount | Interest rate |
| Early Results | May eliminate a small loan sooner | May take longer to eliminate the first loan |
| Total Interest | May cost more | Generally costs less |
| Motivation Style | Progress through small victories | Progress through long-term savings |
Which Method Clears Student Loans Faster?
If your main goal is to minimize interest and repay all your debt as efficiently as possible, the Debt Avalanche Method is generally the mathematical winner.
However, the exact payoff date depends on your loan balances, interest rates, payment amount, and repayment terms.
The snowball method may eliminate your first individual loan sooner. But paying off one small loan first does not automatically mean you will eliminate all your debt sooner.
Think about your own habits before choosing.
If you need visible achievements to remain consistent, the snowball method may be easier to maintain. If you can follow a repayment plan without needing frequent early victories, the avalanche method may help you save more money.
The best method is the one you can realistically follow while meeting your other financial obligations.
2026 Autopay Tip: Use the Federal Student Loan Interest Discount
Your repayment strategy is important, but you should also pay attention to available interest-rate benefits.
One useful feature for eligible federal student loan borrowers is automatic payments, commonly called autopay.
Under the standard Direct Loan autopay benefit, eligible borrowers receive a 0.25 percentage-point interest rate reduction while enrolled in automatic debit.
However, there is an important 2026 update.
Starting July 1, 2026, eligible federal Direct Loan borrowers can receive a temporary 1 percentage-point interest rate reduction through June 30, 2028. To qualify for this temporary benefit, eligible borrowers must enroll by December 31, 2026, and meet the program requirements.
The benefit generally applies to eligible Direct Loans originated on or after July 1, 2012. Other federal loan types may not qualify for the additional reduction.
How to Set Up Autopay
Follow these steps:
- Visit StudentAid.gov and sign in to your account.
- Review your federal student loan information and identify your loan servicer.
- Visit your servicer’s official website.
- Find the automatic payment or autopay option.
- Review the eligibility requirements and confirm your bank account information.
- Check your account regularly to make sure payments are being withdrawn correctly.
Important: Autopay is not a replacement for a repayment strategy. It helps make payments consistently and can reduce your interest rate if your loans qualify.
Keep enough money in your linked bank account before each scheduled withdrawal. Also, review your loan statements to confirm that the correct payment amount is being deducted.
Conclusion: Choose One Strategy and Take Your First Step Today
Student loan debt can feel like a long road, especially when you are starting your career and managing new financial responsibilities.
But you do not need a complicated repayment system to make progress. You need to understand your loans, choose a repayment order, and remain consistent.
The Debt Snowball Method focuses on smaller balances and psychological motivation. The Debt Avalanche Method focuses on higher interest rates and reducing total interest costs.
Neither approach is automatically right for everyone.
If visible progress helps you stay committed, consider the snowball method. If reducing interest costs is your priority, the avalanche method is generally the stronger mathematical choice.
Your Actionable Next Step
Set aside 20 minutes today and complete these tasks:
- List every student loan you currently have.
- Write down each outstanding balance.
- Record the interest rate and minimum monthly payment.
- Check whether each loan is federal or private.
- Choose either the snowball or avalanche repayment order.
- Review your budget and decide how much extra you can realistically pay without neglecting essential expenses or emergency savings.
Then, make your first repayment plan.
You do not have to eliminate your entire student loan balance this month. You just need to know which loan comes first and what your next payment will accomplish.
A clear plan, followed consistently, can turn a stressful debt balance into a manageable financial goal.

Legal Disclaimer
This article is for educational and informational purposes only and should not be considered financial, legal, tax, or investment advice. Student loan repayment options, interest rates, eligibility requirements, and federal policies can change. Individual results depend on loan terms, income, repayment choices, and other financial circumstances. Always review your loan documents and consult your loan servicer or a qualified financial professional before making significant repayment decisions. Visit Federal Student Aid for official information about federal student loan repayment options and current program requirements.
Related Articles
The 50/30/20 Budget Rule Explained for Beginners (A Simple Guide to Managing Money Without Stress)
A simple framework for organizing needs, wants, and savings without making your budget feel overwhelming.
Emergency Fund 101: How Much Money Should You Really Save?
A practical next read for building a financial cushion for unexpected expenses.
10 Money Habits That Keep People Poor (Without Them Realizing)
Explore the everyday money behaviors that can quietly make saving and wealth-building harder.
Cash Stuffing vs Digital Budgeting: Which One Actually Helps You Save More?
Compare a traditional cash-based approach with modern digital budgeting.
The Hidden Cost of Lifestyle Inflation (And How to Escape It)
See how higher income can disappear when spending rises just as quickly.
Why Most People Never Become Financially Free
Learn how spending, saving, debt, and everyday financial habits can shape long-term financial freedom.
How to Build Wealth Even If You Start Late
A useful follow-up for readers who want to turn better saving habits into long-term wealth.