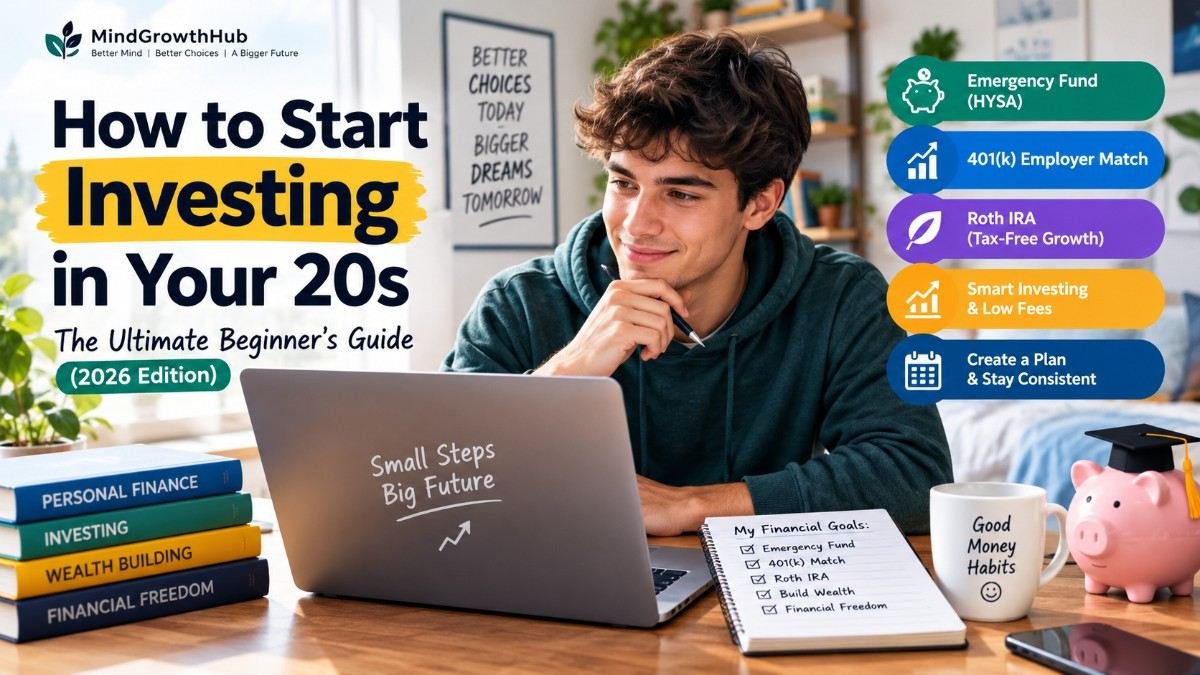
Your 20s Are the Best Time to Start Investing
Imagine two friends, Alex and Jordan, who want to build wealth for retirement. Both earn similar salaries, live in the same city, and eventually invest the same amount of money each month.
There is just one difference: Alex starts investing at age 22, while Jordan waits until age 32.
That ten-year head start could make a difference of hundreds of thousands of dollars by retirement. The reason is compound interest, one of the most powerful concepts in personal finance.
Compound growth happens when your investment earnings generate additional earnings over time. Instead of making money only on your original contributions, you begin earning returns on previous returns, too.
And the longer your money has to grow, the more powerful this effect can become.
The best part? You do not need a six-figure salary, a finance degree, or thousands of dollars sitting in your checking account to begin investing.
You need a plan, a basic understanding of your options, and the willingness to start with what you can afford.
Whether you are a college student working part-time, a recent graduate paying off student loans, or a young professional starting your first full-time job, this guide will show you how to start investing in your 20s in 2026.
We will cover emergency savings, employer-sponsored retirement plans, Roth IRAs, beginner-friendly investments, and common mistakes to avoid.
Let’s get started.
Table of Contents
Why Starting Early Makes Such a Big Difference
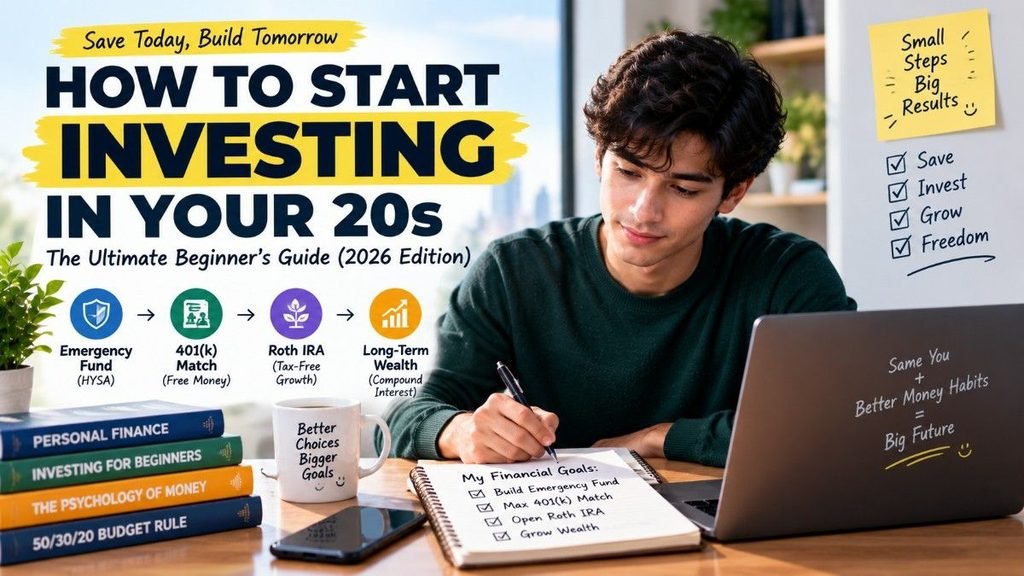
Before choosing an investment account, understand why time matters so much.
Suppose you invest $200 every month beginning at age 22. You continue until age 65, contributing a total of $103,200 over 43 years.
Now imagine you wait until age 32 and invest that same $200 every month until age 65. Your total contributions would be $79,200 over 33 years.
For a simplified illustration, assume both investments earn an average annual return of 7%, compounded monthly, with contributions made at the end of each month.
| Starting Age | Monthly Investment | Years Invested | Approximate Value at 65 |
| 22 | $200 | 43 | $631,000 |
| 32 | $200 | 33 | $324,000 |
These are hypothetical estimates, not guaranteed investment results. Actual returns fluctuate, and taxes, fees, inflation, and market conditions can affect your outcome.
The difference is approximately $307,000, even though the monthly investment amount is identical.
Why? Alex’s money has an additional decade to benefit from potential growth.
This example illustrates an important lesson: starting early can matter more than starting big.
You do not have to invest hundreds of dollars immediately. Even $25, $50, or $100 per month can help you develop consistent habits while your income grows.
The goal is not to become wealthy overnight. It is to give your money enough time and opportunity to work toward your future goals.
Step 1: Build an Emergency Fund Before Taking Major Investment Risks
Investing is important, but your financial foundation matters just as much.
Imagine you invest most of your savings in the stock market and then your car breaks down, your laptop stops working, or you suddenly lose your job. You may need to sell investments at an inconvenient time to cover the expense.
An emergency fund helps prevent that situation.
What Is an Emergency Fund?
An emergency fund is money reserved for unexpected expenses, such as:
- Medical bills and unexpected healthcare costs.
- Car repairs or urgent transportation expenses.
- Temporary unemployment or reduced income.
- Essential home repairs.
- Unexpected travel for a family emergency.
This money should be accessible when you need it and should not depend on the stock market performing well.
How Much Should You Save?
A common starting goal is $500 to $1,000, especially if you are a college student or just beginning your career.
Once you have established that initial cushion, work toward saving three to six months of essential living expenses. Your ideal target depends on your income stability, monthly obligations, insurance coverage, and personal circumstances.
For example, if your essential expenses total $2,000 per month, three months of expenses would equal $6,000.
You do not need to save the entire amount immediately. Set a manageable monthly goal and build your emergency fund gradually.
Why a High-Yield Savings Account Makes Sense
A high-yield savings account, commonly called an HYSA, pays interest on your savings. These accounts can offer significantly higher yields than traditional savings accounts, although rates vary and can change.
They are useful for emergency funds because they generally offer easier access to cash than long-term investments.
A high-yield savings account is not designed to make you rich. Its purpose is to help protect your savings while earning interest.
Top High-Yield Savings Accounts to Compare in October 2026
The following comparison uses the supplied October 2026 rate information. APYs are variable unless an account’s terms specify otherwise, and actual eligibility and minimum-balance requirements should be confirmed before opening an account.
| Bank or Platform | Advertised APY | Minimum Deposit or Balance | Best For |
| Peak Bank | 4.27% | $100 minimum to open | Savers who can meet the opening deposit |
| CIT Bank Platinum Savings | 4.25% | $5,000 minimum balance to earn the top rate | People maintaining a larger savings balance |
| NexBank via Raisin | 4.25% | Minimal opening balance; check current offer terms | Savers comfortable opening an account through an online platform |
| Elevault | 4.34% | Minimal opening balance; verify current terms | People comparing digital savings options |
Rates and terms are time-sensitive and may change. The rates above are the supplied October 2026 figures, not a guarantee of the rate available when you apply. CIT Bank’s top rate requires a $5,000 minimum balance under the supplied terms. NexBank’s availability through Raisin and Elevault’s account terms should be checked directly. Verify fees, withdrawal procedures, promotional restrictions, and applicable FDIC insurance before depositing money.
Which High-Yield Savings Account Should You Choose?
The highest APY is not automatically the best choice for everyone.
Peak Bank may be worth considering if you can meet its $100 opening deposit and prefer a straightforward savings account.
CIT Bank Platinum Savings may suit someone with at least $5,000 available to maintain the balance required for its advertised top rate. Check what rate applies if your balance falls below that threshold.
NexBank through Raisin offers another route to an online savings account. Before opening one, understand the platform’s account-opening process, transfer times, promotional conditions, and how deposit insurance applies to the underlying bank.
Elevault is another option to investigate if its current rate and account terms match your needs.
Compare accessibility, fees, account requirements, and deposit protection alongside APY. A slightly lower rate may be preferable if the account is easier to use and better suited to your financial needs.
How Much Interest Could Your Savings Earn?
Suppose you keep $5,000 in an account earning 4.27% APY for one year.
If the rate remained unchanged for the entire year and you made no withdrawals or additional deposits, you would earn approximately $213.50 in interest.
Your ending balance would be approximately $5,213.50.
That is money your savings could earn without exposing your emergency fund to stock market fluctuations. Actual earnings depend on the bank’s rate, balance calculations, and account terms.
Important: Savings interest is generally taxable at the federal level and may also be taxable at the state level. Keep that in mind when estimating your after-tax earnings.
Once your emergency fund is on track, you can begin putting more attention toward long-term investments.
Step 2: Get the Free Money From Your Employer’s 401(k) Match
If your employer offers a 401(k) retirement plan with matching contributions, it deserves your attention.
An employer match is money your employer contributes to your retirement account based on how much you contribute yourself, subject to the plan’s rules.
It is one of the most valuable benefits available to eligible employees.
How Does a 401(k) Match Work?
Imagine your employer matches 100% of your contributions up to 3% of your salary.
If your annual salary is $50,000 and you contribute 3%, you put $1,500 into your 401(k) over the year.
Your employer could contribute another $1,500, assuming you satisfy the plan’s matching requirements.
That brings the total contribution to $3,000 before any investment gains or losses.
If you fail to contribute enough to receive the full available match, you could miss out on part of the benefit your employer offers.
This is why a common starting strategy is to contribute enough to your 401(k) to receive the full employer match, provided you can cover your essential expenses and maintain an appropriate cash cushion.
Read your plan documents carefully because matching formulas, vesting schedules, and eligibility requirements differ between employers.
The 2026 401(k) Contribution Limit
For 2026, the employee elective deferral limit for most traditional 401(k) plans is $24,500.
The overall annual contribution limit for defined contribution plans is generally $72,000, subject to compensation limits and applicable plan rules. This overall limit generally includes employee contributions and employer contributions, but excludes eligible catch-up contributions.
Employees age 50 and older may qualify for an additional $8,000 catch-up contribution in 2026. A special higher catch-up limit of $11,250 applies to eligible participants ages 60 through 63 under the relevant rules.
These are maximums, not targets you must reach immediately. Most people in their 20s can start with a much smaller percentage of their paycheck and increase contributions as their earnings grow.
For current official details, consult the IRS 401(k) contribution limit guidance.
Traditional 401(k) vs. Roth 401(k)
Your employer may offer a traditional 401(k), a Roth 401(k), or both.
A traditional 401(k) generally allows eligible contributions to reduce your current federal taxable income, while withdrawals in retirement are generally taxable.
Roth 401(k) contributions are made with after-tax dollars. Qualified withdrawals, including eligible investment earnings, can generally be taken tax-free.
Which option makes more sense depends on factors such as your current tax bracket, expected future income, and retirement goals. You do not have to predict your future perfectly to get started.
If you are early in your career and currently have a relatively low taxable income, a Roth option may be worth considering. However, compare the potential tax benefits rather than assuming one option is always better.
What Should You Invest in Inside Your 401(k)?
Your 401(k) is an account, not an investment by itself. The money generally needs to be allocated among the investments available in your employer’s plan.
Common choices include:
- Target-date retirement funds: These hold a mix of investments and gradually adjust their allocation as a selected retirement year approaches.
- Broad-market index funds: These aim to track a market index and may provide diversified exposure to many companies.
- Bond funds: These can provide exposure to bonds, although they still carry risks, including interest-rate and credit risk.
Check your plan’s fees, investment options, and risk information before choosing.
For beginners who prefer a simple approach, a diversified target-date fund can be worth researching. Make sure you understand its investment strategy, expenses, and whether it fits your timeline and risk tolerance.
Step 3: Consider a Roth IRA for Tax-Free Qualified Retirement Withdrawals
Once you have addressed urgent financial needs and are taking advantage of an available employer match, a Roth IRA may be a useful next step.
A Roth IRA is an individual retirement account that offers a different tax structure from a traditional IRA.
You contribute money that has already been taxed. If you meet the requirements for a qualified distribution, you can withdraw the money and investment earnings tax-free in retirement.
That can be particularly appealing to young investors who expect their income to increase over the course of their careers.
What Is the Roth IRA Contribution Limit for 2026?
For 2026, the annual IRA contribution limit is $7,500 for individuals under age 50, subject to eligibility rules.
The catch-up contribution limit for eligible individuals age 50 and older is $1,100, making the total potential contribution $8,600.
Your combined contributions to traditional and Roth IRAs generally cannot exceed the applicable annual IRA limit. You also need eligible compensation, such as wages or qualifying self-employment income, to contribute, subject to the applicable rules.
You do not need to contribute the full $7,500 to benefit from a Roth IRA. A smaller automatic monthly contribution can help you build a consistent habit.
For example, investing $100 per month adds up to $1,200 in annual contributions.
Roth IRA Income Limits for Single Filers
Your ability to contribute directly to a Roth IRA depends partly on your modified adjusted gross income, or MAGI, and your tax-filing status.
For single filers in 2026, the supplied limits are:
- Below $153,000 MAGI: Eligible for the full contribution, subject to other requirements.
- $153,000 to less than $168,000 MAGI: The allowable contribution phases out.
- $168,000 or above MAGI: No direct Roth IRA contribution is generally allowed under the single-filer income limits.
The phase-out is not an all-or-nothing rule at the lower threshold. If your income falls within the phase-out range, your permitted contribution is reduced.
The income thresholds are different for other filing statuses, including married couples filing jointly. Check the IRS’s 2026 retirement contribution announcement for the official limits.
Why a Roth IRA Can Be Useful in Your 20s
The main advantage is the potential for decades of tax-free growth followed by qualified tax-free withdrawals.
Consider a hypothetical investor who contributes $250 each month for 40 years. That equals $120,000 in total contributions before considering investment growth.
If the investments grow over time, the account could eventually be worth considerably more than the amount contributed. With a Roth IRA, qualified withdrawals can generally include both the original contributions and earnings without additional federal income tax.
Actual results depend on market performance, investment choices, fees, and tax rules.
What Should You Buy Inside a Roth IRA?
Opening the account is only the first step. You must also choose how the money will be invested.
Depending on the provider, common options may include:
- Broad-market stock index funds.
- Total-market funds that hold many different companies.
- International stock funds.
- Bond funds.
- Target-date retirement funds.
A diversified portfolio can help spread risk across different investments, but diversification does not eliminate the possibility of losing money.
Choose an allocation that reflects your time horizon, comfort with market fluctuations, and financial circumstances. Avoid buying an investment simply because it has recently performed well.
Also, remember that a Roth IRA is not automatically invested when you deposit money. Some accounts may leave contributions in cash until you choose an investment.
Review your account to confirm that your money is allocated according to your plan.
Step 4: Learn the Basics of Investing Before Picking Individual Stocks
Investing does not have to mean spending hours researching individual companies or checking stock prices throughout the day.
For many beginners, a diversified, low-cost investment approach is a more manageable starting point than attempting to predict which company will perform best next month.
Understand the Main Investment Types
Stocks: When you buy a stock, you own a share of a company. Stocks offer growth potential but can lose substantial value, particularly over short periods.
Bonds: Bonds are debt investments issued by governments, municipalities, or companies. Their risks depend on the issuer, interest rates, and other factors.
Mutual funds and ETFs: These investment vehicles pool money to hold a collection of assets. Depending on the fund, they may provide exposure to hundreds or thousands of securities.
Index funds: These funds aim to track a specific market index rather than actively select investments in an attempt to outperform the market.
For beginners, broad diversification and low fees can be useful considerations. Neither guarantees positive returns.
Why Low Fees Matter
Investment fees may seem small, but they can reduce your long-term results.
Imagine two similar investments with different annual expense ratios. If one charges substantially more than the other, the difference can compound over many years.
Before investing, check the expense ratio, account fees, transaction costs, and any other charges that apply.
Do not choose a fund based on fees alone. Consider its investment objective, holdings, risk, and suitability as well.
Avoid Trying to Time the Market
Market timing involves attempting to predict when prices will rise or fall so you can buy or sell at the most advantageous moment.
Even experienced investors can struggle to do this consistently.
A more practical approach for many long-term investors is to establish a reasonable investment plan and contribute regularly, rather than making frequent decisions based on headlines or short-term price movements.
Investing on a schedule can help create discipline. However, regular investing does not guarantee a profit or protect against losses during a declining market.
Step 5: Create a Monthly Investing Plan You Can Actually Maintain
A good financial plan should work with your real life, not an imaginary budget where you never have unexpected expenses.
If you are a college student, your income may change between semesters. If you have recently started working, you may be adjusting to rent, transportation, student loan payments, and other bills.
Start with a realistic amount and build from there.
Example: A Beginner’s Monthly Plan
Imagine a young professional earns $3,000 per month after taxes.
A simplified plan might look like this:
| Category | Monthly Amount |
| Housing, utilities, and groceries | $1,500 |
| Transportation and essential bills | $400 |
| Debt payments | $250 |
| Emergency savings | $250 |
| Retirement investing | $300 |
| Flexible spending and other goals | $300 |
| Total | $3,000 |
This is only an example. Your own budget may look very different depending on your housing costs, income, family support, debts, and other obligations.
If you have high-interest credit card debt, it may make sense to prioritize paying it down while contributing enough to receive an available employer match, depending on your circumstances.
If your income is irregular, build a plan around your average take-home pay and keep enough cash available for essential expenses.
Automate Your Contributions
Automation can make investing easier to maintain.
Consider setting up automatic transfers to your savings account and automatic retirement contributions through your employer’s payroll system.
You can also schedule recurring transfers to an IRA or brokerage account, if appropriate.
Start with an amount you can afford without relying on credit cards to cover routine bills. Increase it gradually when you receive a raise, reduce an expense, or improve your financial situation.
Consistency matters, but so does flexibility. If an unexpected emergency arises, revisit your plan instead of forcing contributions you cannot afford.
Step 6: Avoid These Common Investing Mistakes in Your 20s
Starting early is valuable, but avoidable mistakes can undermine your progress.
1. Investing Without Any Emergency Savings
If every dollar is invested, an unexpected bill could force you to sell assets when markets are down.
Build a reasonable cash cushion and expand it as your financial responsibilities grow.
2. Waiting Until You Feel Rich Enough
You do not need a large salary to learn how investing works.
Start with education, a manageable savings goal, and a contribution amount that fits your budget. You can increase it as your circumstances improve.
3. Ignoring Your Employer’s Retirement Benefits
If you have access to a 401(k) match, understand how it works and what you need to contribute to receive the full benefit.
Review the plan’s vesting rules and deadlines, too.
4. Chasing Hype and Quick Profits
Social media often highlights dramatic gains without giving equal attention to losses, uncertainty, or risk.
Avoid making financial decisions simply because an influencer claims a stock or other asset is about to take off. Research investments carefully and never invest money you need for immediate expenses in volatile assets.
5. Paying High Fees Without Understanding Them
Fees can quietly reduce returns over time.
Read the account’s fee schedule and fund documents before investing, and compare similar options where appropriate.
6. Checking Your Investments Every Day
Frequent checking can encourage emotional decisions based on ordinary market movements.
For long-term investments, consider reviewing your portfolio periodically and when your goals or financial circumstances change. Avoid reacting automatically to every market headline.
7. Forgetting That Your Goals Will Change
Your financial priorities at age 22 may differ from those at age 29.
You might move to a new city, pursue graduate school, buy a home, or support family members. Review your savings, investment allocation, and cash needs as your life changes.
A flexible plan is more useful than one you abandon because it no longer fits your circumstances.
A Simple 30-Day Plan to Start Investing in Your 20s
You do not have to accomplish everything in one weekend.
Use this practical checklist to take your first steps over the next month.
Week 1: Understand Your Money
- Review your income and essential expenses.
- List your debts, minimum payments, and interest rates.
- Decide on an initial emergency-fund target.
- Check whether your employer offers a retirement plan and matching contributions.
Week 2: Set Up Your Savings
- Compare high-yield savings accounts.
- Review minimum balances, fees, access, and deposit insurance.
- Start saving an affordable amount toward emergencies.
- Make a plan for upcoming expenses.
Week 3: Review Retirement Accounts
- Learn how your employer’s 401(k) works.
- Check the employer-match formula and vesting requirements.
- Research Roth IRA eligibility and the 2026 contribution limits.
- Compare investment options, fees, and tax treatment.
Week 4: Start With a Manageable Contribution
- Choose an amount that fits your budget.
- Set up automatic contributions where appropriate.
- Select investments only after understanding their risks and costs.
- Schedule a monthly review of your progress.
At the end of 30 days, you do not need to have a perfect portfolio or a fully funded emergency account. You simply need a clearer plan and a repeatable system for making progress.
Frequently Asked Questions About Investing in Your 20s
How much money should I have before I start investing?
There is no universal minimum amount of savings you must have before investing. Your starting point depends on your financial obligations, income stability, emergency savings, and debt.
Consider building an initial emergency cushion and taking advantage of an available employer match when it fits your circumstances. You can then expand your savings and investment contributions over time.
Is a Roth IRA better than a 401(k)?
Neither account is automatically better for everyone.
A 401(k) may offer an employer match and higher annual employee contribution limits. A Roth IRA can offer tax-free qualified retirement withdrawals and may provide a different range of investment choices.
Your employer’s benefits, current income, tax situation, and long-term goals all matter. Some investors use both accounts.
Can college students start investing?
Yes, college students can learn about investing and may be eligible to contribute to retirement accounts if they meet the applicable requirements, including having eligible compensation for IRA contributions.
Students should also consider tuition, housing, emergency savings, and other near-term expenses before committing money to investments that can lose value.
Are high-yield savings accounts safe?
Savings accounts at FDIC-insured banks are generally insured up to applicable limits, subject to ownership-category rules and other conditions. Deposit insurance does not cover losses in stocks, ETFs, or mutual funds.
Before opening an account through a savings platform, confirm which bank holds the deposit and how insurance applies to your specific account.
What is the biggest advantage of investing early?
Time gives long-term investments more opportunity to compound.
Starting earlier can also help you develop consistent financial habits before your expenses and responsibilities become more complicated. Returns are never guaranteed, but time can be a meaningful advantage.
Should I pay off student loans before investing?
It depends on the loan interest rate, repayment terms, your financial cushion, and whether your employer offers a retirement match.
High-interest debt may deserve priority because paying it down reduces the interest you would otherwise owe. Lower-interest student loans may be manageable alongside retirement saving, depending on your circumstances.
Compare the guaranteed cost of your debt with the uncertain returns of investing, and avoid assuming that investment gains will necessarily exceed your loan interest.
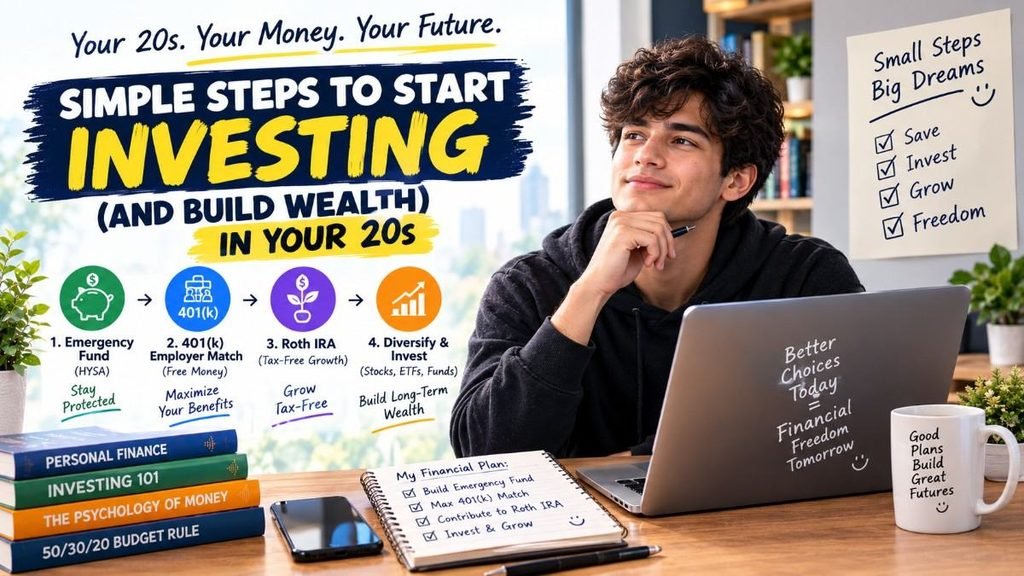
Conclusion: Start Small, Stay Consistent, and Give Your Money Time
Learning how to start investing in your 20s is not about finding a secret stock or getting rich quickly. It is about building habits that give your money a chance to grow over time.
You do not need to earn a huge salary or invest every spare dollar to begin.
Start with an emergency fund, understand your employer’s 401(k) match, explore Roth IRA eligibility, and choose investments that align with your timeline and tolerance for risk.
As your income grows, consider increasing your contributions and reviewing your financial plan regularly.
Most importantly, remember that investing is a long-term process. Markets fluctuate, financial priorities change, and no strategy guarantees a particular outcome.
Your biggest advantage in your 20s is the time ahead of you. Use it wisely, start with what you can afford, and focus on progress rather than perfection.
Key Takeaways
- Build an emergency fund: Work toward an initial cash cushion and eventually three to six months of essential expenses, as appropriate.
- Compare high-yield savings accounts: Review APY, minimum balances, fees, access, and deposit insurance.
- Capture your 401(k) employer match: Understand your employer’s matching rules and contribute enough to receive the available match when financially practical.
- Know the 2026 limits: The employee 401(k) contribution limit is $24,500, and the annual IRA limit is $7,500 for eligible individuals under age 50.
- Explore a Roth IRA: Understand its income limits, contribution requirements, and qualified tax-free withdrawal rules.
- Keep investing simple: Learn about diversification, investment fees, and the risks of individual investments.
- Automate what you can afford: Consistent contributions can help turn investing into a habit.
- Think long term: Avoid chasing quick profits and making emotional decisions based on short-term market movements.
Financial Disclaimer
This article is for informational and educational purposes only and should not be considered financial, investment, tax, or legal advice. The information presented is general in nature and may not be appropriate for every individual’s financial circumstances. Investment products involve risk, including the potential loss of principal. Past performance does not guarantee future results, and hypothetical examples are not predictions of actual investment performance. Savings account interest rates, account terms, retirement contribution limits, and tax rules may change. Before making financial decisions, verify current information with the relevant financial institution, the Internal Revenue Service, or a qualified financial, tax, or legal professional. Readers are responsible for evaluating their own financial circumstances and making decisions that align with their needs and goals.
Related Articles
The 50/30/20 Budget Rule Explained for Beginners (A Simple Guide to Managing Money Without Stress)
A simple framework for organizing needs, wants, and savings without making your budget feel overwhelming.
Emergency Fund 101: How Much Money Should You Really Save?
A practical next read for building a financial cushion for unexpected expenses.
10 Money Habits That Keep People Poor (Without Them Realizing)
Explore the everyday money behaviors that can quietly make saving and wealth-building harder.
Cash Stuffing vs Digital Budgeting: Which One Actually Helps You Save More?
Compare a traditional cash-based approach with modern digital budgeting.
The Hidden Cost of Lifestyle Inflation (And How to Escape It)
See how higher income can disappear when spending rises just as quickly.
Why Most People Never Become Financially Free
Learn how spending, saving, debt, and everyday financial habits can shape long-term financial freedom.
How to Build Wealth Even If You Start Late
A useful follow-up for readers who want to turn better saving habits into long-term wealth.